PNB Luxura Metal Card Review: Worth Activating in 2026?
📅 Updated as of 3 Oct 2026. Card details from PNB’s official LUXURA pages and FAQ. We’ll update this review after our first two statements.
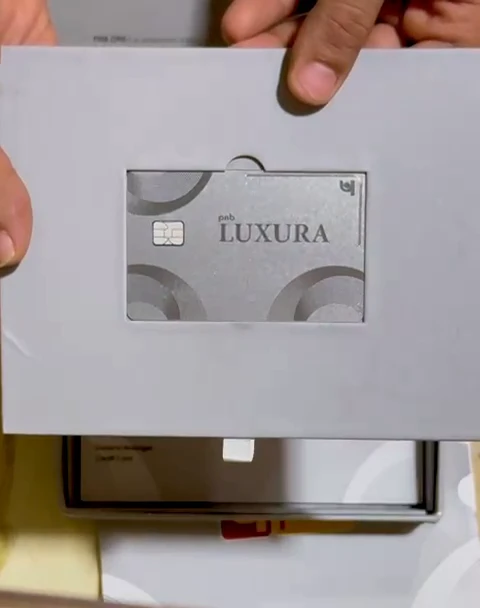
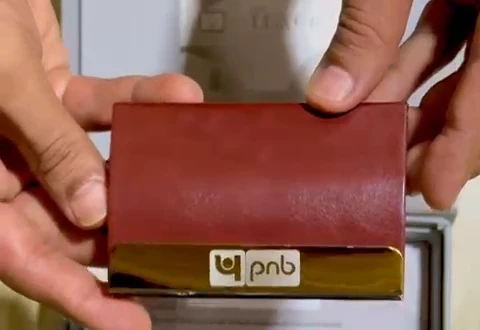
A grey box from Punjab National Bank landed on our desk this week. Inside: the PNB Luxura metal credit card on RuPay, plus a leather card holder as a welcome gift. A public sector bank doing a metal card with zero forex and unlimited lounges? We were sceptical too. Here’s what it actually offers, where it beats our other cards, and whether you should activate it.
TL;DR
- 💳 Fee (RuPay, the card we got): ₹9,000 + GST joining (waived on ₹2.5 lakh spend in the first 90 days), ₹7,500 + GST a year from year two (waived on ₹8 lakh a year). The Visa Infinite version costs less: ₹4,999 + GST and ₹1,999 + GST.
- 🎁 Welcome bonus: 40,000 points (₹10,000) on ₹50,000 spend in 90 days, double the Visa version’s 20,000.
- 🎯 Rewards: 4 points per ₹100 (1% back, 1 point = ₹0.25), 3X on travel and dining (3%), plus 10,000 milestone points (₹2,500) at ₹5 lakh a year.
- 🌍 Zero forex markup. Rare in India, and the card’s biggest strength.
- 🛋️ Unlimited domestic and international lounge access per PNB’s terms, with no spend condition listed.
- 🧾 Few exclusions: PNB’s published terms exclude fuel and cash withdrawals. Most premium cards pay nothing (or very little) on utilities, insurance, government payments and rent. We’re testing these and will report back.
- ✅ Verdict: Activate it if you can hit ₹2.5 lakh in the first 90 days. It’s a great second card for foreign spends, lounge access and the categories your main card ignores.
PNB Luxura at a glance
| Network | RuPay (metal). A Visa Infinite version is also sold, with lower fees and half the welcome bonus |
| Joining / annual fee | ₹9,000 + GST / ₹7,500 + GST (₹10,620 / ₹8,850 with GST) |
| Fee waivers | Joining fee waived on ₹2.5 lakh in the first 90 days (3 billing cycles); annual fee waived on ₹8 lakh a year |
| Base rewards | 4 points per ₹100 = ₹1 (1%) |
| Travel and dining | 3X = 12 points per ₹100 (3%) |
| Welcome bonus | 40,000 points (₹10,000) on ₹50,000 spend in 90 days |
| Milestone | 10,000 points (₹2,500) at ₹5 lakh annual spend |
| Forex markup | Nil |
| Lounges | Unlimited, domestic and international |
| Golf | 4 rounds or lessons a year (one per quarter) |
| Insurance | Air accident ₹1 crore, personal accident ₹50 lakh, purchase protection ₹2 lakh |
| RuPay extras | Can be linked to UPI (reward rules on UPI not yet published by PNB); HoteLux Elite Plus membership leaflet in our welcome kit |
The real advantage: categories other cards ignore
Over the last two years most premium cards have stopped paying rewards on rent, utilities, insurance and government payments, or capped them hard. That’s where Luxura and the IndusInd Avios card stand out.
| Category | Axis Magnus | HDFC Infinia | IndusInd Avios | PNB Luxura |
|---|---|---|---|---|
| Utilities and telecom | ❌ 0 | Capped (2,000 points a month) | ✅ ~0.6–0.75% | ✅ 1%* |
| Insurance | ❌ 0 | Capped (10,000 points a month) | ✅ ~0.6–0.75% | ✅ 1%* |
| Government and tax | ❌ 0 | ❌ 0 | ✅ ~0.6–0.75% | ✅ 1%* |
| Rent | Check terms | ❌ 0 | Check terms | 1%* (to be confirmed) |
| Fuel | ❌ 0 | ❌ 0 | ❌ 0 | ❌ 0 (surcharge waiver only) |
Example: a ₹1 lakh annual health insurance premium earns nothing on Magnus. On Luxura, if it earns as the terms suggest, that’s 4,000 points (₹1,000). It also counts towards the ₹8 lakh annual fee waiver and the ₹5 lakh milestone.
PNB Luxura vs IndusInd Avios
| PNB Luxura (RuPay) | IndusInd Avios Visa Infinite | |
|---|---|---|
| Fees | ₹9,000 + ₹7,500 a year, both waivable (₹2.5 lakh / ₹8 lakh) | ₹10,000 joining, ₹5,000 renewal |
| Welcome | 40,000 points (₹10,000) on ₹50k spend | 20,000 Avios (~₹24,000–30,000) |
| Base earn | 1% cash-like value | 3 Avios per ₹200 (~1.8–2.25%) |
| Travel | 3% on travel and dining | 5 Avios per ₹200 on BA flights; 6 per ₹200 at preferred international destinations |
| “Excluded” categories | 1% (fuel and cash excluded) | 1 Avios per ₹200 on utilities, education, government, insurance |
| Milestones | 10,000 points (₹2,500) at ₹5 lakh | 18,000 Avios at ₹8 lakh and again at ₹16 lakh |
| Forex | 0% | 1.5% at preferred destinations |
| Lounges | Unlimited | 2 per quarter |
| Best for | Foreign spends, lounges, bills other cards ignore | Building Avios for Qatar and BA awards |
The two cards do different jobs. IndusInd Avios gives more value per rupee if you redeem Avios well (Qatar Qsuites, BA short-haul). Luxura wins on convenience: zero forex, unlimited lounges, and a welcome bonus that covers the joining fee even if you miss the waiver. Holding both makes sense if you spend abroad and travel often.
RuPay Ekaa: RuPay’s answer to Visa Infinite
Our Luxura is built on RuPay Ekaa, the top tier of NPCI’s RuPay network. Each network has a similar ladder, and the tier decides the network-level perks your bank can add on top of its own benefits.
| Tier | RuPay | Visa | Mastercard |
|---|---|---|---|
| Entry | Platinum | Platinum | Platinum |
| Premium | Select | Signature | World |
| Super-premium | Ekaa | Infinite | World Elite |
- Ekaa perks on cards like Luxura include ITC stay, dining and spa offers, HoteLux hotel membership, OneVasco visa-centre lounges, golf and movie offers.
- The big RuPay plus is UPI. A RuPay credit card can be linked to UPI apps and used to scan-and-pay at shops. Visa and Mastercard credit cards can’t. Check your bank’s terms for whether UPI spends earn points.
- The Visa plus is acceptance abroad. RuPay works overseas through partner networks (Discover, Diners, JCB and others), but coverage is patchier than Visa or Mastercard. Carry a backup card when you travel.
- Other Ekaa cards include Union Bank’s NEXTERIA and Indian Overseas Bank’s RuPay Ekaa card, with more banks adding the tier.
You can choose the network: the RBI rule
Since 6 September 2024, RBI requires card issuers with more than 10 lakh active credit cards to let eligible customers choose from multiple card networks when a card is issued, and existing cardholders at their next renewal (RBI circular, 6 March 2024). For Luxura, PNB already sells both a RuPay and a Visa Infinite version. Want the cheaper Visa fees, or RuPay’s UPI and bigger welcome bonus? Ask for the version you want when you apply or renew. A switch usually means a new card with a new number.
What we don’t like
- No airline or hotel transfer partners that we can find. Points are worth a flat ₹0.25, so there’s no upside from clever redemptions.
- 1% base is ordinary. Magnus and Infinia beat it on regular spends.
- High fees on RuPay. ₹7,500 + GST a year unless you spend ₹8 lakh, and no renewal benefit beyond the waiver. If you’re applying fresh and don’t need UPI, the Visa version is far cheaper.
- Unproven servicing. Our application took over 20 days and a follow-up email. PNB’s credit card operations are new to premium cards.
- Fine print still to be tested: the exact 3X merchant list, caps (if any) and how lounge access works in practice.
Should you activate it?
| You are… | What to do |
|---|---|
| Travelling abroad in the next few months | ✅ Activate. Zero forex plus unlimited lounges. Use it for travel bookings and spends abroad, especially if you don’t have a Magnus month going. |
| Paying insurance, utilities, school fees or taxes on a card that earns nothing | ✅ Activate and move those bills here. Even 1% beats zero, and it helps you hit the ₹2.5 lakh joining-fee waiver. |
| Can’t spend ₹2.5 lakh in the first 90 days | ⚠️ You’ll pay ₹10,620 with GST, but the 40,000-point welcome bonus (₹10,000) on just ₹50,000 almost cancels it out. Activate only if the lounges and zero forex matter to you. |
| Won’t spend ₹8 lakh a year on it | ⚠️ Plan to downgrade or close before the second-year fee of ₹8,850 with GST hits. |
| Already juggling 5+ premium cards | 🤔 Activate for lounges and foreign spends only; don’t let it pull spend away from your main points card. |
Our plan: we’re activating it, putting insurance and utility bills on it to clear the ₹2.5 lakh fee waiver and the ₹50,000 welcome-bonus spend, and using it abroad. We’ll report back on how the “excluded” categories actually earn, how quickly points post, and how lounge entry works.
DealUni verdict
Not a points-maximiser’s main card, but a very good second card: zero forex, unlimited lounges and 1% on the bills that other premium cards ignore. The RuPay fees are steep, but the welcome bonus pays for year one and ₹8 lakh a year waives the rest. Activate it, give it the spends your main card doesn’t reward, and keep your big category spends on Magnus or Infinia.
Sarkari bank ka metal card, aur kaam ka bhi. (A government bank’s metal card, and a useful one too.)
Want to see how Luxura fits with your other cards? Try the DealUni AI Planner, or read our guide to airline credit cards in India.
Card details from PNB’s official LUXURA (RuPay & Visa) FAQ and LUXURA card page; RuPay fee-waiver thresholds from PNB’s launch terms (Dec 2025). IndusInd Avios earn rates from British Airways’ official card page. Avios valued at ₹1.20–1.50 (DealUni data, Sep 2026). Exclusions for Magnus and Infinia from DealUni’s card data. We received our Luxura card in October 2026 after applying in August.