Best Credit Cards on a ₹30–50k Salary (and the Gift Card Trick)
Updated as of 6 Oct 2026. Card terms and gift card discounts change often, so we’ve dated every figure. Discounts were checked on 6 Oct 2026.
Most Indian salaries sit between ₹30,000 and ₹50,000 a month. That rules out Infinia, Magnus and most metal cards, and a lot of card advice online simply isn’t for you. Good news: you don’t need a premium card to earn well. You need one or two simple cards and the habit of buying gift cards before you spend. Done right, a basic card plus a voucher discount can return more than a premium card paying directly.
The formula: voucher discount + card reward
Instead of paying a brand directly, buy its gift card on a voucher platform at a discount, pay for that gift card with a card that still earns on it, then spend the gift card. You collect two discounts on the same rupee:
- The voucher discount: about 2–5% on everyday brands, and 14–26% on movies, food and hotel vouchers.
- The card reward: 1–5%, if your card pays on gift card purchases. Many don’t any more; see the card list below.
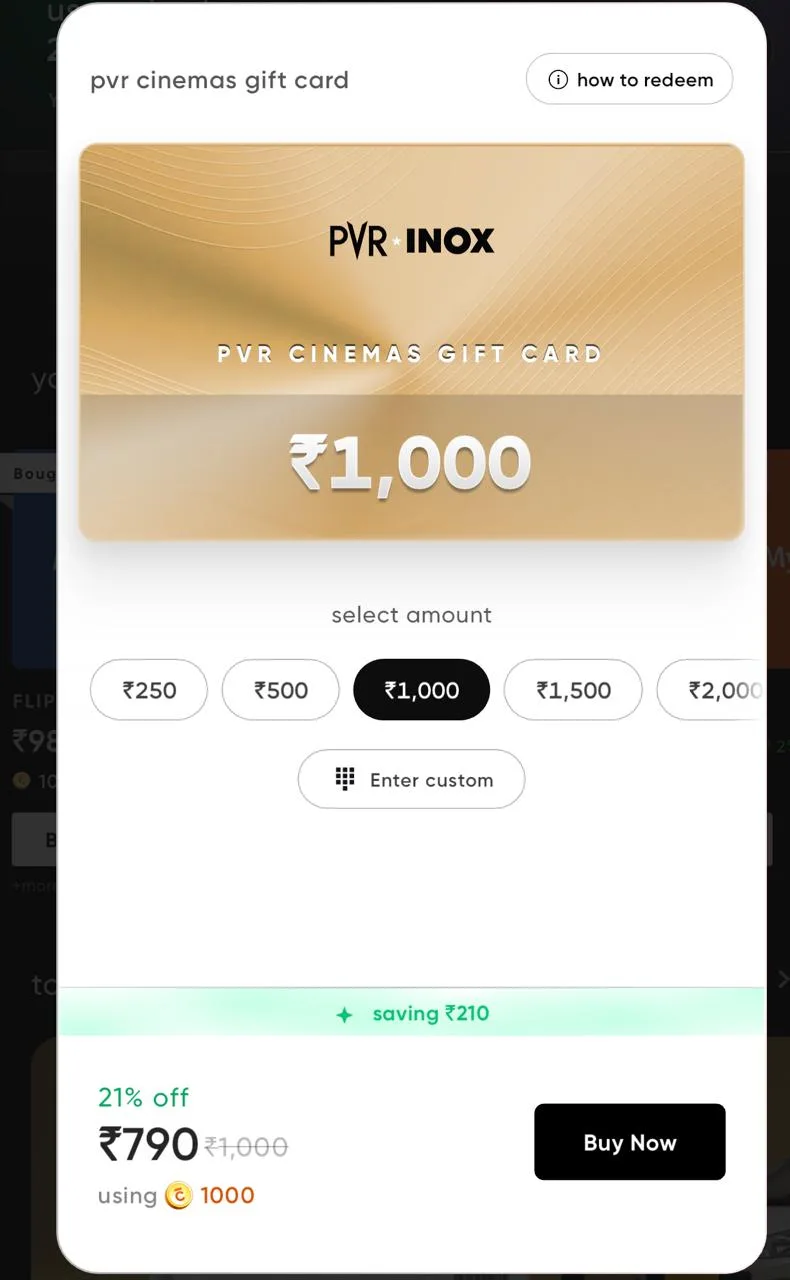
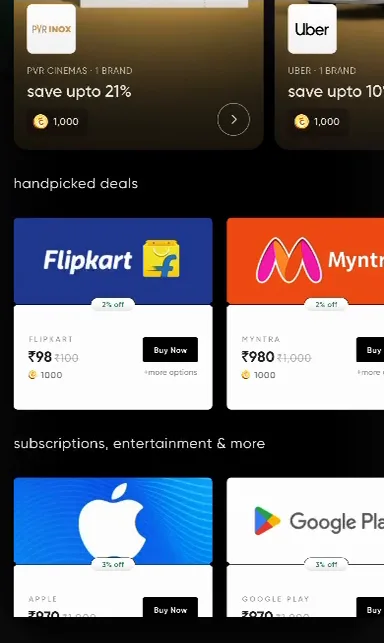
Example: two PVR INOX tickets for ₹1,000. Pay directly with a 1% card and you get ₹10 back. Buy a PVR INOX voucher on CRED at 21% off and you pay ₹790, plus whatever your card earns on the ₹790. That’s over ₹200 saved on one movie night.
Picture abhi baaki hai, mere dost. (The picture isn’t over yet, my friend.)
The 3 basic cards worth having
| Card | Fee | Income (salaried) | What it earns | On gift cards |
|---|---|---|---|---|
| Amazon Pay ICICI | Lifetime free | ₹30,000/month | 5% on Amazon with Prime (3% without), 2% on Amazon Pay categories including bill payments, 1% elsewhere. No caps | 2% on gift cards bought on Amazon.in (Amazon shows it on the listings) |
| SBI Cashback | ₹999 + GST, waived on ₹2 lakh a year | Not published | 5% online (max ₹2,000 a month), 1% offline (max ₹2,000). Nothing on transactions under ₹100 | No blanket ban, but wallet loads and gift-shop merchant codes are excluded. Test first (see below) |
| HDFC Millennia | ₹1,000 + GST, waived on ₹1 lakh a year | ₹35,000/month (age 21–40) | 5% at 10 merchants including Amazon, Flipkart, Swiggy and Myntra (max 1,000 CashPoints a month), 1% elsewhere (max 1,000) | Only 1%, including vouchers bought on SmartBuy |
Start with Amazon Pay ICICI. It’s free forever, the income bar is published and low, and it pays 2% on bills through Amazon Pay, which most other cards now exclude. Add SBI Cashback as a second card if you spend ₹15,000 or more online a month: 5% online is the best flat rate a basic card offers. Pick HDFC Millennia instead if you earn ₹35,000+ and shop mostly on Amazon, Flipkart and Swiggy, or if you want to start an HDFC relationship (useful later, see below).
Cards that don’t work for gift cards
These are fine cards for direct spending, but their terms exclude gift cards in writing, so they don’t fit this strategy:
- Every Axis card (Flipkart Axis, ACE, Airtel Axis and the rest): no rewards, cashback or milestone credit on gift cards since 28 Aug 2026.
- Swiggy HDFC: gift cards, wallets and SmartBuy are excluded from cashback.
- Tata Neu HDFC: no NeuCoins on “Gift or Prepaid Card load / Voucher purchase”.
- HSBC Live+: gift cards are excluded from its 1.5%.
Amazon Pay: the G.O.A.T. of gift cards
Most voucher tricks work only at one brand. Amazon Pay balance works almost everywhere you’d otherwise earn nothing. According to Amazon’s own guide, you can use it for:
- Bills: electricity, water, piped gas, LPG cylinders, mobile postpaid and prepaid, broadband and landline, DTH.
- Insurance premiums, including motor insurance from Acko, HDFC Ergo and ICICI Lombard.
- FASTag recharges (ICICI FASTag) and metro cards in select cities.
- Shopping on Amazon.in and Amazon Fresh, train tickets, and partner apps such as Swiggy, Zomato, Uber and BookMyShow.
Bills, insurance and FASTag are exactly the spends most cards exclude. Amazon Pay turns them into something you can earn on.
Bijli ka bill bhar rahe ho? Cashback bhi le lo. (Paying the electricity bill anyway? Take the cashback too.)
How to earn on it, by card:
| You hold… | Best way to pay bills | What you get |
|---|---|---|
| Amazon Pay ICICI | Pay each bill on Amazon Pay with the card itself | 2%, unlimited (rent, tax and education excluded) |
| SBI Cashback | Buy an Amazon Pay gift card on Amazon.in with the card, then pay bills from the balance | Up to 5%, if the purchase codes as an online spend. Buy one ₹500 card first and check that the cashback posts on your statement before going bigger |
| HDFC Millennia | Buy Amazon Pay gift cards on SmartBuy at 1% off (max ₹10,000 a month) | 1% off + 1% back |
Amazon Pay gift card rules (from the issuer’s T&C):
- Valid for 1 year.
- Maximum ₹10,000 per card.
- No refunds, transfers or cash-out.
- Can’t buy other gift cards, Kindle or app-store content.
- Buy only what you’ll spend in the next month or two.
Where the big discounts are
Amazon Pay is for coverage. The big percentages come from brand vouchers, and you don’t need a special app: Amazon.in and Flipkart sell them too. Here’s the best price we found for each brand on 6 Oct 2026:
| Brand | Best discount we found | Where |
|---|---|---|
| Cinepolis | up to 26% | CRED |
| PVR INOX | 21% (16% on Gyftr) | CRED |
| Domino’s | 17% (15% on Gyftr) | CRED |
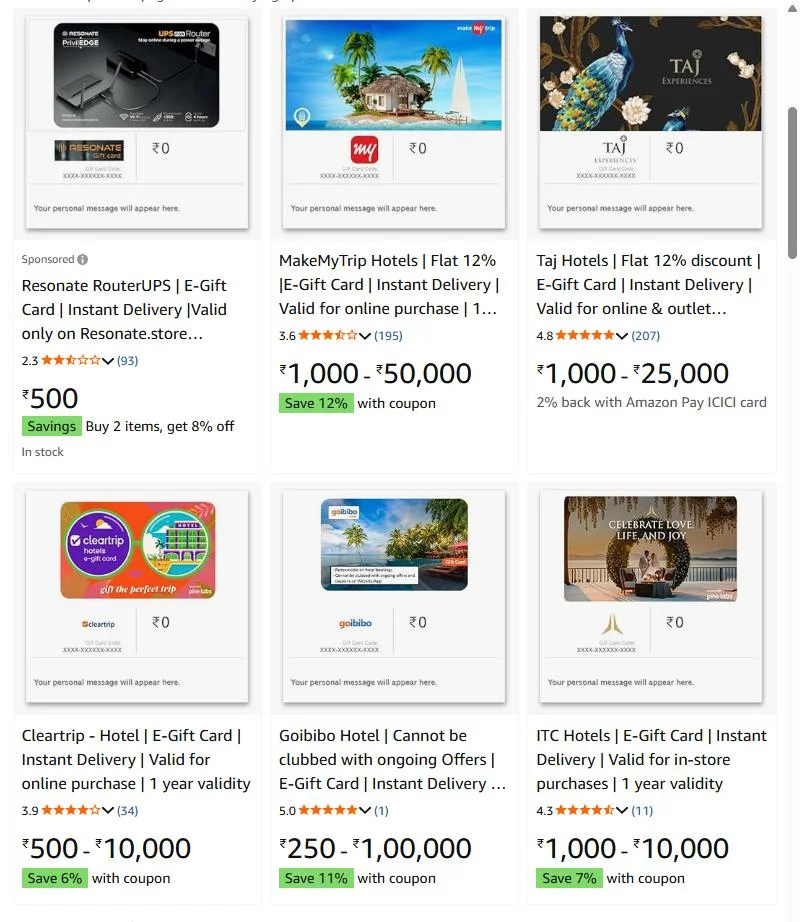
| Goibibo hotels | 16% (11% on Amazon) | Woohoo |
| MakeMyTrip hotels | 14% (12% on Amazon) | Woohoo |
| Yatra hotels | 13% | Amazon |
| Taj Hotels | 12% | Amazon |
| Starbucks | 12–13% (8% on Gyftr) | CRED |
| Uber | 10% | CRED |
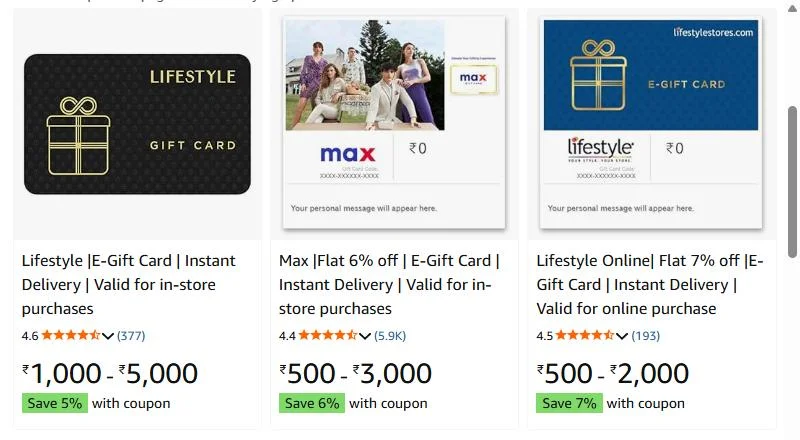
| Max | 6–8% | Amazon |
| AJIO | 8% | Woohoo |
| Lifestyle | 5–7% | Amazon |
| Pantaloons | 7% | Gyftr |
| ITC Hotels | 6–7% | Amazon |
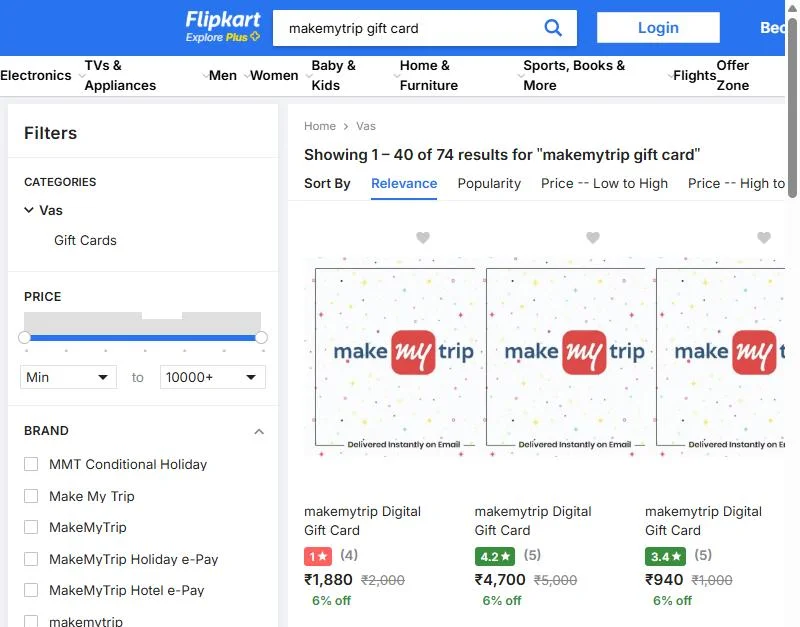
| MakeMyTrip (flights, holidays) | 6% | Flipkart, Amazon |
| BigBasket | 3–6% | CRED |
| Myntra | 2–4.5% | Flipkart, Gyftr (with a code) |
| Croma | 3% | Gyftr, Woohoo |
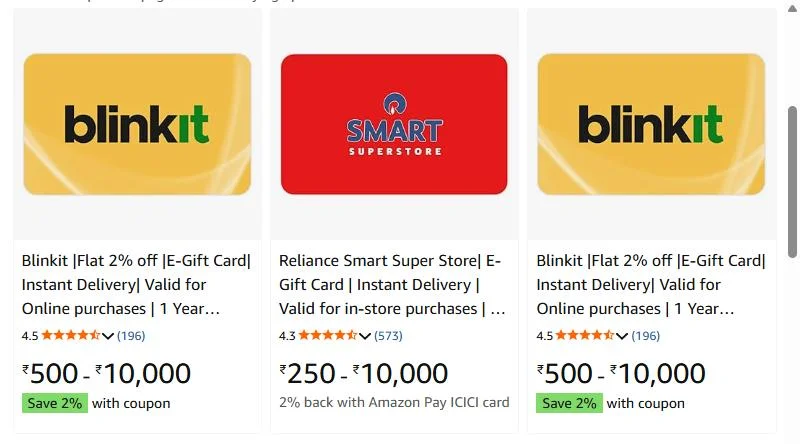
| Swiggy, Blinkit | 2% | Amazon |
| Flipkart | 2–4% | CRED |
| Amazon Shopping Voucher | 1.75% | Gyftr |
Simple rule: if the voucher discount is under about 3% and your card already pays 5% at that merchant, just pay directly. Vouchers win on movies, food, travel and fashion. More on CRED’s store in our CRED gift cards review.
Bonus for Amazon Pay ICICI holders: brand e-gift cards on Amazon.in show “2% back with Amazon Pay ICICI card” right on the listing. So a Taj Hotels card at 12% off becomes about 14% once the card’s 2% lands, and a Max card at 6% becomes about 8%.
If you can get one premium card, make it this
On a ₹30,000–50,000 salary, banks won’t give you a premium card on income alone. Two other routes work: a fixed deposit (FD), or a relationship value (savings + FDs + investments held with one bank).
Route 1: a card against an FD
| Card | FD needed | Fee | Why |
|---|---|---|---|
| IDFC FIRST WOW! Black | ₹20,000 | ₹750 + GST, waived on ₹1.5 lakh a year | Zero forex markup, UPI via a RuPay virtual card, airport lounge access with a monthly spend condition. The best FD-backed card for travel |
| ICICI Coral (against FD) | ₹50,000 (180+ days) | ₹500 + GST, waived on ₹1.5 lakh | Limit up to 90% of the FD. A solid way to start an ICICI history |
| HDFC against FD | Ask your branch | Same as the regular card | HDFC lists FD-backed cards but doesn’t publish which variants. Ask for Millennia, or Regalia Gold if your FD is large |
Your FD keeps earning interest, and on-time payments build your credit score. After 6–12 months of clean repayment, ask the bank to move you to an unsecured card and release the FD. No bank guarantees this, but a clean record is your best case.
Route 2: a relationship with one bank
| Programme | What you need (any one) | Realistic? |
|---|---|---|
| ICICI Wealth | ₹10 lakh in deposits + savings balance | The lowest bar we found. Premium cards like Sapphiro and Emeralde are offered here, at the bank’s discretion |
| Axis Priority / IDFC FIRST Select | ₹15 lakh relationship value | A stretch, but possible with family savings in one place |
| Axis Burgundy | ₹30 lakh relationship value | Unlocks Magnus for Burgundy, one of India’s best travel cards |
| HSBC Premier, StanChart Priority | ₹50 lakh | Not for now |
Don’t lock money you might need into a bank just for a card. But if your savings already sit in FDs, moving them to one bank can unlock a card you’d otherwise need a ₹3 lakh salary for.
Who should do what
| You are… | What to do |
|---|---|
| Getting your first card | Amazon Pay ICICI. Pay every bill through Amazon Pay with it. |
| Spending ₹15,000+ online a month | Add SBI Cashback for 5% online, and test it on an Amazon Pay gift card. |
| Earning ₹35,000+, shopping mostly on Amazon, Flipkart and Swiggy | HDFC Millennia, and buy vouchers on SmartBuy. |
| Travelling abroad even once a year | IDFC FIRST WOW! Black against a ₹20,000 FD for zero forex. |
| Holding ₹10 lakh+ in FDs | Consolidate with one bank and ask for its wealth-tier card. |
Rules that keep this profitable
- Pay the full bill, every month. Interest of 3–4% a month wipes out a year of cashback in one statement.
- Buy gift cards only for spending you’ve already planned. A discount on something you didn’t need is a loss.
- Use official platforms only: the brand, Amazon, Flipkart, CRED, Gyftr, SmartBuy or Woohoo. “Discounted codes” on Telegram or WhatsApp are scams.
- Watch the caps: SBI Cashback’s ₹2,000 a month online, Millennia’s 1,000 CashPoints, SmartBuy’s ₹10,000 a month on Amazon vouchers.
- Two cards are enough. More cards means more fees, more due dates and more chances to miss one.
Jitni chaadar ho, utne hi pair phailao. (Stretch your legs only as far as your sheet goes: spend within your means.)
DealUni take
A ₹40,000 salary and a free Amazon Pay ICICI card, used properly, beat a ₹10,000-fee card used lazily. Route bills through Amazon Pay, buy vouchers for movies, food, travel and fashion, and keep the card count low. When you’re ready to step up, an FD card like WOW! Black is the cheapest door into travel rewards. Then plan your first points trip with the Trip Spend Planner.
Gift card pehle, swipe baad mein. (Gift card first, swipe later.)